Piggy Bank Allowance - Bomad

- 46.00 Reviews
- 4.4
- Downloads
- 50,000+
Our take on Piggy Bank Allowance - Bomad from Appgk
I like the idea behind Piggy Bank Allowance - Bomad because it treats pocket money as something children can practise managing, rather than simply receiving. After spending time with this parenting app, I found its most useful role is as a shared routine between an adult and a child: agree on an allowance, record it, separate money for different purposes, and talk through choices before the balance disappears. It is free to install, aimed at Everyone, and developed by Graeme P, so it feels more like a focused family tool than a large finance platform.
The app has earned a 4.4 average from around 700 ratings, with more than 50 thousand installs. Those figures suggest that its simple approach has found an audience, but simplicity is also the key to judging it fairly. This is not a replacement for a bank account, a card for children, or a full household budgeting system. I see it as a visual allowance tracker built around virtual pocket money and separate saving and spending jars or pots. For families that want a calm, repeatable way to teach money habits, that focus is useful. For families looking for automation, real payments, or detailed reports, it may feel limited.
How the everyday allowance routine works
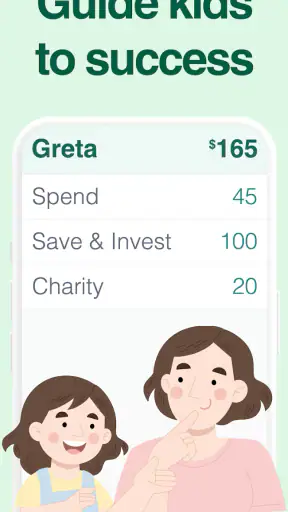
The most sensible way to begin is to keep the first setup deliberately small. I would start with one child, one allowance arrangement, and a couple of clear pots. A spending pot can represent money the child may use soon, while a saving pot gives longer-term goals a visible place. The important point is not to create a perfect financial model on the first day. It is to make the balance understandable enough that a child can explain where the money is going.
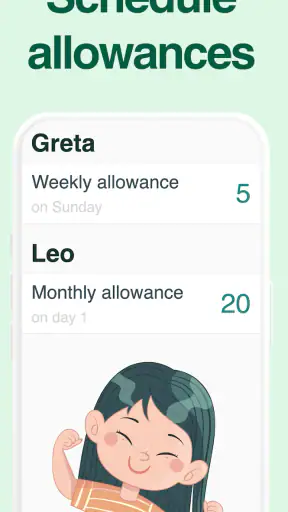
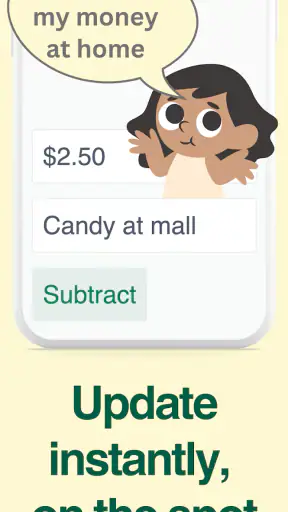
A practical weekly routine might look like this. On the agreed allowance day, the adult opens the app with the child and records the amount. Together, they decide whether it belongs entirely in spending or should be divided between spending and saving. If the child later chooses a small treat, the adult records the deduction from the spending pot. When the child receives extra money for a particular reason, that can be treated as a separate decision instead of being mixed invisibly into the regular allowance.
Best Parts of Piggy Bank Allowance - Bomad
Things to Keep in Mind About Piggy Bank Allowance - Bomad
This manual approach is one of the app’s strengths and one of its weaknesses. It encourages conversation because the adult and child actively acknowledge each transaction. At the same time, it depends on someone remembering to keep the virtual balances current. If entries are made several days late, the app stops reflecting the child’s real decisions and becomes an unreliable record. I would therefore attach the update to an existing habit, such as the weekly family planning session or the moment allowance is handed over.
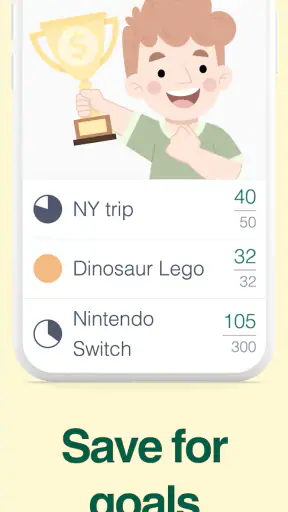
The jars or pots are especially helpful for children who understand pictures and categories better than abstract numbers. Instead of hearing that money should be “managed responsibly,” a child can see that a portion is reserved and another portion is available. That distinction creates a useful pause before spending. It also makes delayed rewards easier to discuss: the saving pot can show progress even when the goal is still far away.
News and Features Related to Piggy Bank Allowance - Bomad

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Make the first categories meaningful
I would avoid creating pots for every possible purpose. Too many categories turn a simple allowance into clerical work, especially for younger children. A spending pot and a saving pot are enough to establish the basic habit. A third category may make sense for giving or a specific shared goal, but only if the family will actually use it consistently.
There is also a subtle difference between a saving pot and a promise to save. The pot gives the child a visible place for reserved money, but it does not make the decision automatically. The adult still needs to agree on what counts as saving, when money can be moved, and whether a child may change their mind. I found that this conversation matters more than the number displayed on screen. Without a family rule, a saving pot can become just another spending balance with a delay attached.
Don't want to read the full review?
For younger children, I would use plain language and let them choose familiar goals. For older children, the same structure can support more thoughtful conversations about trade-offs. A child might decide that saving half of an allowance slows down immediate purchases but makes a larger goal possible. The app does not need to lecture them; the visible separation does much of the teaching.
Use it as a conversation tool, not a punishment system
The tracker works best when it records agreed choices rather than policing every mistake. If a child spends everything in the spending pot, I would use that moment to review what happened and ask whether the next allowance should be divided differently. Treating the app as a scoreboard for good and bad behaviour can make money feel like a source of conflict.
Screenshots
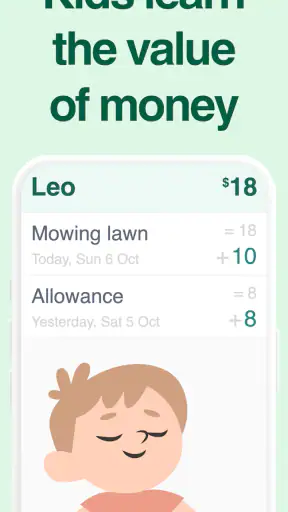
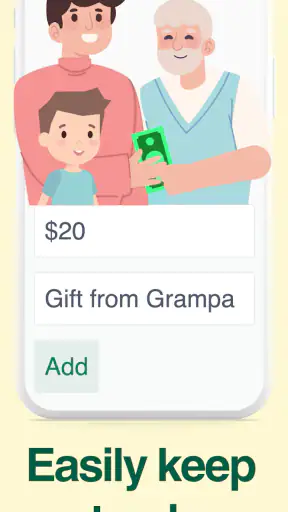
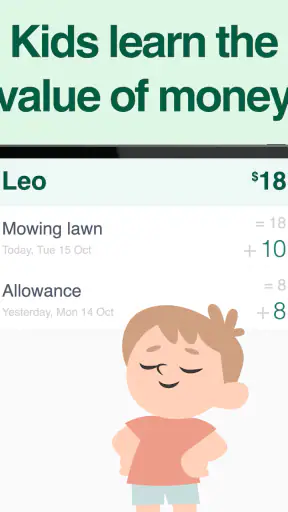
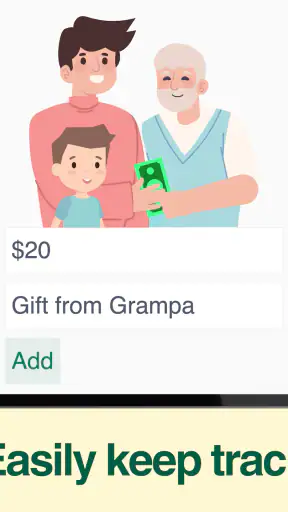
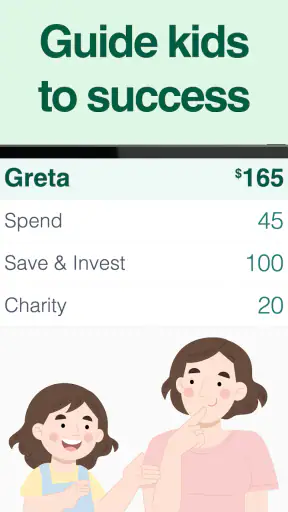
It is also worth deciding in advance how chores, gifts, and unexpected payments fit into the routine. The app can help you record the result, but the family still supplies the rules. A clear agreement prevents arguments such as whether a birthday gift belongs in the allowance or whether a completed task earns extra money. Keeping those decisions consistent makes the balances more useful over time.
Settings and setup choices that deserve attention
The most valuable setup work is not cosmetic. It is deciding how the app will match the family’s actual allowance rhythm. Before entering anything, I would settle whether the child receives money weekly, occasionally, or only after particular responsibilities. I would also decide who is responsible for recording changes. If both parent and child assume the other person will do it, the tracker will quickly drift away from reality.
Because the app is centred on virtual money, the adult should explain exactly what the balance means. It may represent cash held at home, an agreed future payment, or simply a learning exercise. Those interpretations are not interchangeable. If the child sees a balance as money they can spend immediately but the adult sees it as a promise for later, the app will create confusion rather than clarity.
I would also check the available app settings during the initial setup instead of rushing past them. The current version is 2.0.266 and requires Android 9 or later, so compatibility is a practical first check for families using an older device. On a supported phone, take a moment to review how the child’s profile, allowance details, and pots are arranged. A tidy starting structure reduces the temptation to rebuild everything after the first few entries.
The app is free, but it includes in-app purchases ranging from $1.99 to $29.99 per item. I would not treat those purchases as necessary before establishing whether the basic workflow suits your household. Use the free experience first, observe whether everyone remembers to update it, and only then consider whether an optional purchase solves a real problem for your family. A paid addition cannot compensate for an allowance routine that nobody follows.
Choose a review rhythm before you choose more features
A useful setting in practice is the family’s own review rhythm, even when it is not an app control. I recommend a short check at the same time each allowance cycle. Look at the spending pot, look at the saving pot, and ask one question about a recent choice. This turns the tracker into a habit instead of a screen that is opened only during disagreements.
For a child who is just learning, you may want to update the app together every time. For an older child, you can let them make the entry and explain it afterward. That gradual handover is a better measure of progress than simply watching the balance grow. The app’s value increases when responsibility moves from adult-managed recording toward child-led reflection.
Another useful choice is deciding how precise the system should be. If the family is tracking tiny amounts, record them accurately enough to support the lesson, but do not let rounding become a weekly argument. The purpose is to make decisions visible. Excessive precision can distract from the more important question: did the child understand why money was placed in a particular pot?
Faster patterns for families who use it regularly
Once the basic routine is stable, I found that speed comes from repeating the same sequence rather than searching for clever shortcuts. Open the app, add the allowance, divide it between the established pots, and review the result with the child. Keeping the order consistent makes the process easier to remember and reduces accidental omissions.
A helpful pattern is to separate allowance day from shopping day. On allowance day, record and divide the money. On shopping day, discuss the intended purchase before changing the spending balance. This creates a small planning window and prevents every request from turning into an immediate transaction. It also lets a child see the difference between wanting something and deciding to use money for it.
Another efficient approach is to use one saving goal at a time for younger children. If several goals compete for attention, the child may lose track of why money is being reserved. A single visible target gives the saving pot a clear purpose. Older children may manage multiple priorities, but I would add them only after they can explain the difference between money available now and money reserved for later.
Experienced users can also make the app part of a short monthly reset. Review what was spent, what was saved, and whether the original division still makes sense. The reset is not about deleting history or pretending earlier choices did not happen. It is a chance to adjust the routine when a child’s needs change, such as moving from mostly saving toward a balance that allows some independent spending.
Use real-world moments to keep the virtual balance honest
The strongest workflow connects an entry to something the child can see. If cash is placed in an envelope, update the corresponding virtual pot at the same time. If a purchase is made, record it while the receipt or item is still present. This simple pairing prevents the app from becoming an abstract game disconnected from household life.
For families who do not use physical cash, the adult can still create the same connection by treating the app balance as an agreed record. Before approving a purchase, check the spending pot together. Afterward, subtract the amount and talk briefly about the remaining balance. The child learns that a digital number has consequences without needing access to a financial account.
I would avoid updating several weeks in one sitting unless there is no alternative. Backfilling loses the useful detail of individual choices and makes it harder for a child to remember what happened. If the family misses a week, record the correction openly and restart the routine rather than trying to reconstruct every small event perfectly.
Where the app’s limits become important
The main limitation is that this is a tracker, not a complete money-management service. It does not replace a child’s bank account, a payment card, or a system that moves real funds automatically. If your priority is teaching a child to use contactless payments, monitor real transactions, or manage money independently through a financial institution, a dedicated banking product will be a better fit.
The manual nature also means the app is only as reliable as the adults and children using it. A family with several children, irregular payments, shared expenses, and frequent adjustments may find the pot structure too simple. You can still use it as a learning aid, but maintaining many parallel balances could become more work than the lesson is worth.
I would also be cautious about using it as the sole record for formal household accounting. Its purpose is child-friendly allowance practice, not detailed financial documentation. Keep any important receipts, agreements, or real-money records in the system your household already trusts. The virtual balance should support the conversation, not carry responsibilities it was not designed to handle.
The age rating of Everyone makes the app approachable for a broad family audience, but that does not mean every child will benefit in the same way. A very young child may need an adult beside them to interpret the pots. A teenager who already uses a bank account may find the visual system too basic unless the family uses it specifically for allowances and saving goals. The right age depends more on the child’s independence and the family’s routine than on the rating alone.
There is also a trade-off between flexibility and consistency. Families often want to change the rules when a child asks for an exception, but frequent exceptions make the balance difficult to interpret. I recommend agreeing on what can change and what cannot. For example, the child might choose how to divide a regular allowance while the adult decides how unusual payments are recorded. That boundary keeps the app flexible without making every entry negotiable.
When another option is the better choice
Choose a different type of tool if you need automatic recurring transfers, linked accounts, spending alerts, or a verified record of real transactions. Those features belong to banking and financial-management services rather than a simple allowance tracker. Likewise, if your main goal is chore scheduling, you may prefer an app built around tasks and responsibilities, with money as a secondary reward.
On the other hand, a spreadsheet may be less suitable for younger children even if it gives adults more control. A spreadsheet can calculate totals, but it usually does not make the saving-versus-spending decision as easy to discuss. Piggy Bank Allowance - Bomad is most convincing when the child is meant to participate in the process, not merely appear as a row in an adult’s records.
Families should also think about the purchase model before committing to a long-term setup. The app costs nothing to download, while optional in-app items range from $1.99 to $29.99. I would keep the basic routine independent of those extras and make a purchase only when its value is clear to the people actually using the app. That keeps the learning habit from becoming dependent on spending more.
My verdict after building a repeatable habit
After testing the workflow, I see this parenting app as a practical middle ground between loose verbal promises and a full child-friendly banking service. It gives allowance a visible structure without pretending to handle real financial infrastructure. The saving and spending pots are the central idea, and they work best when an adult uses them to create regular, short conversations about choices.
My strongest recommendation is to keep the system boring in a good way. Use a small number of pots, update them at a fixed time, connect entries to real events, and review the arrangement when the child’s needs change. Those habits matter more than adding complexity. The app becomes genuinely useful when it reduces repeated explanations and gives the child something concrete to refer to.
I would recommend it to parents who want to introduce allowances gradually, especially when the goal is understanding rather than financial independence. It is also a good fit for families that prefer to keep real bank accounts separate from early money lessons. The free starting point makes it easy to try, and the Everyone rating keeps it accessible for a wide range of households.
I would skip it if you expect automatic tracking, real payments, detailed family accounting, or a complete chore-and-reward platform. Its manual workflow requires participation, and its simplicity will feel restrictive to families with complicated allowance arrangements. Those are not minor details; they define whether the app will become a useful weekly tool or another forgotten icon.
Overall, I think Piggy Bank Allowance - Bomad succeeds when it is treated as a shared practice space for money decisions. It will not teach budgeting on its own, but it can make the first steps visible, repeatable, and easier to discuss. If you set clear rules, keep the pots meaningful, and update the balances while events are fresh, it offers a straightforward way to help a child connect earning, saving, and spending with everyday choices.
Piggy Bank Allowance - Bomad FAQ
What is Piggy Bank Allowance - Bomad, and who is it designed for?
Piggy Bank Allowance - Bomad is a family-focused allowance management app designed to help parents organize children’s pocket money, chores, savings, and spending habits. It provides a simple way to record allowances and encourage financial responsibility without relying on paper charts or informal reminders. The app is mainly useful for families who want children to understand how earning, saving, and managing money work in everyday life.
How does the allowance and chore system work in the app?
Parents can generally use Piggy Bank Allowance - Bomad to set up children’s profiles, define regular allowance amounts, and connect payments with completed chores or responsibilities. This makes it easier to track what has been earned and why. Before downloading, parents should review the available settings because the exact chore, reward, scheduling, and approval options may vary depending on the app version and device platform.
Can children use the app independently, or does it require a parent account?
The app is intended to support supervised family use, so parents will usually need to create or manage the household setup before children can view their allowance information. Children may be able to check balances, tasks, or savings progress, but financial decisions and account controls are generally handled by the parent. Families should confirm the login, profile, and permission requirements during setup.
Does Piggy Bank Allowance - Bomad transfer real money or connect to a bank account?
Piggy Bank Allowance - Bomad should be viewed primarily as a tracking and teaching tool rather than an automatic banking service. Recording an allowance in the app does not necessarily transfer money to a child or connect directly to a bank account. Parents may still need to pay cash or use their preferred payment method separately. Check the current store description for supported payment features and regional limitations.
Is Piggy Bank Allowance - Bomad safe for children, and what should parents check before downloading?
Because the app deals with children, allowances, and potentially family information, parents should review its privacy policy, permissions, data collection practices, and account security before installation. It is also worth checking whether the app contains advertising, subscriptions, or in-app purchases. Keep parental controls enabled, avoid sharing unnecessary personal details, and download only from the official Google Play or Apple App Store listing.